Showing posts with label Economics. Show all posts

Sunday, June 30, 2013

How to invest hedge funds and index funds?


Most investors, thanks to partly financial regulations, invest their  money in index funds. These funds usually invest in all stocks –including failing companies and stocks with sky-high valuations and in fact aren't the right choice for most investors. Last decade was a good example: S&P 500 index has lost 24.8% in the ten years between 2000 and 2010 even when you take the dividends into account. While indexes performed poorly, talented hedge fund managers like billionaire David Einhorn returned 249.4% after fees and expenses during the same 10 years! Not only that, in fact, he has beaten the market in every single year.

But as you may have known, if you are not very rich, you cannot invest in hedge funds. In fact, even the very rich can’t invest in the most successful hedge funds because most of them are closed to new investors.

So your only option seems to use your own time and knowledge to pick stocks to invest. But just in USA markets, there are more than 6000 publicly traded companies. You probably don’t have the knowledge, resources, or time to follow and analyze all of these companies.

But there are some other options for retail investors out there. One of them is Insider Monkey.

Insider Monkey, one of the fastest growing financial research websites on the web, read by 1.5 million people every month, is a good option to mimic the investments by hedge funds. Although they have a web site with some free content, with a yearly fee, they also offer a premium newsletter that isolates the hottest stocks among the BEST hedge funds.

Insider Monkey is managed by New York based Ian Dogan who has a Ph.D. in financial economics and is an expert in insider trading. He has managed a $200+ million portfolio within a large hedge fund and now he is utilizing his skills to bring alpha generating investment strategies to Insider Monkey’s premium members.

Insider Monkey claims that their 15 Stock Small Cap Strategy has beaten the market by 18 percentage points per year between 1999 and 2009. Since the end of August last year, they have been sharing the stock picks of this strategy and according to them these stocks gained an average of 48.9% between September 4th and May 31st, vs. 17.8% for the S&P 500 index.

The subscription to Insider Monkey quarterly premium newsletter is for $499 per year. Other than quarterly newsletters, subscribers also get monthly mini newsletters. If you would like to see what does newsletter look like, you can download the free edition here.

Disclaimer
This blog article is to provide general information only and should not be treated as an invitation to buy or sell anything.  Users of this article should consider this as a one of the many factors in making their investment decision. Users should make reference to other sources of information and specific investment advice to obtain a more objective view of the market. Asia Singapore shall not be responsible for losses suffered.

Tuesday, November 6, 2012

What Obama's win means for the economy?


US has voted and re-elected their president Barack Obama for a second term. As I was writing this article the counting was not over but the television networks projected that Obama will have a second term as a president. So what does this mean for the world or Singapore?

The main theme of the US election 2012 was economy centered around a very simple basic question: Will we start to do something to fix the underlying problems of the economy and take a pain (as recession) now to prevent a catastrophic disaster (a huge financial depression) in the future, or will we continue to kick the can down the road to prevent pain today (as ballooning the US debt to multi-trillion dollar levels) but risk a huge catastrophic disaster in the future?

I do not like Obama so much and I also did not heat up to Romney. But I believe Barack Obama was leaned to prevent pain now, print more money, balloon the debt and Romney was leaned towards doing something now to start to fix it. And hedonism won once again.

So, there is a good news and a bad news.

Under President Barack Obama, the national debt has ballooned past the $16 trillion mark — a number once inconceivable — and is growing by the second as the federal leviathan feeds on borrowed money.[1] Good news is that, Obama now has motivation to continue to kick the can down the road so the change of having a near future recession is less now.

Bad news is that since he will absolutely do nothing to fix the economy and US debt and worse he will continue to do a lot of things to make them worse (i.e. letting Ben Bernanke to print money and cause more job destroying malinvestments around the globe), the change of a catastrophic financial disaster in the future has increased. So be prepared.

Japan is continuing to throw everything two generations saved and accumulated into debt and is a bug looking for a wind shield. Europe is the same. US is the same. As I said, be prepared.

[1] - Obama's pricey gaffe that's worth talking about

What is the fiscal cliff?


Fiscal cliff or United States fiscal cliff is shorthand term used to describe the effect of a series of enacted legislation which will automatically take effect at midnight on December 31, 2012 as tax increases and spending cuts to reduce the US budget deficit and slow down the growth of US debt. As it happened in United States debt-ceiling crisis in 2011, where a financial crisis started as a debate in the United States Congress about increasing the debt ceiling, the US Congress kicked the can until the very end and let the US economy to come just to the edge of this cliff. So if nothing is done - and nothing is done until this very last months of 2012, taxes will go up and there will be huge spending cuts. Many economists predicts that this will result in a new recession. And US debt situation is so desperate that even all these new tax increases and spending cuts take effect, they will only slow down the growth of US debt.

So within a few weeks, after the new President of The United States is elected, there will be very large debate will erupt in Congress about how to deal with the “Fiscal Cliff” and both sides of the debate will argue that their solution is the best when the other solution is an absolute disaster.

So what is the fiscal cliff? In the The Perils of the Fiscal Cliff [1]  article, John Mauldin explains:
In the third quarter of 2011 the US Congress agreed to rather severe tax increases and spending cuts that would kick in as of January 2013, as a way to get a deal done to increase the debt ceiling.[2] In addition, the Social Security payroll tax cut and extended unemployment benefits are also scheduled to go away in January. All told, if nothing changes, this abrupt shift in fiscal policy would result in a hit to the economy of about $650 billion, or a little more than 4% of GDP, at a time when the economy is likely growing less than 2% a year.

In the video below, David Wessel from Wall Street Journal explains things you need to know about the "fiscal cliff". As he explains the real problem is the US budget (or budget deficit):

"Like any budget, money comes in and money goes out. And more money goes out than comes in, there is a budget deficit. I think we have made things way way to complicated. Let me give you 6 facts about the federal budget, which is pretty much all you need to know:

1 - In 2011, 63% of the all federal spending was on auto-pilot. The money went out the door without any voting in Congress to pay the promises made in the past. To pay social security benefits, medicare benefits for elderly, medicaid for the poor, farm subsidies and of course the interest on the federal debt. 
2 - 1 out of every 4 dollars spend from Us budget goes to healthcare. In 1960, before Medicare and Medicaid, healthcare was less than 10% of the US Federal spending. Today, in 2012, it is 25%. 10 years later, it will hit 33%. 
3 - A lot of people think that US government employs a lot of people and they are right. 4 million people work for the US government. But the fact is, if you fired every single one off them, from the secret service agents standing next to the President to the lady collecting tolls for tickets in Yellow Stone and soldiers in Afghanistan, you save 435 billion dollar in a year. That would not reduce the deficit even 1/3. The point: Closing down federal agencies can save some money: but not nearly enough to solve the problem. 
4 - US spends a lot of money on defense: 700 billion USD only in 2011! That is 1 out of every 5 dollars the US government spends. US defense budget is bigger than the combined defense budget of the next 17 big defense spenders: China, Britain, France, Russia, Saudi Arabia, Japan, Germany, India, Italy, Brazil, South Korea, Australia, Canada, Turkey, U.A.E, Spain and Israel. 
5 - Federal income taxes have been falling for more than 30 years. In 1981, the middle class has paid 19.2% of their income as tax. In 2007, that percentage was 14.3%. So how the government has managed to spend more and more? First, the rich paid more taxes as they have made more income. And US have borrowed! US government has borrowed 36 cents for every dollars spend."
So if you decide how much to spend on benefits, healtcare, how many workers government should employ , how much US should spend on defense and how much tax should people pay, you solve the US debt problem. Everything else is detail. But sorting all these out is the problem because people have different views of the solutions for the very same problem and they cannot decide on the solutions.

There is no good solution to the US fiscal cliff: with huge us debt still growing, there are bad and worse choices. If US does not start to reduce the budget deficit now as the fiscal cliff or as some sort of other solutions, a time will come when the US deficit will be so high and countries lending money to US will require very high interest rates: The result: forceful spending cuts in almost everything. So the question is like do you get some pain today (as a recession) to avoid a big torture in the near future (a great depression) or do you try to postpone the pain and face the torture in the future. 
I believe US, as Europe and Japan, will find a solution to the immediate fiscal cliff problem by kicking the can down the road more and  doing absolutely nothing to address the real structural problems. As John Mauldin repeatedly says, Japan is a bug in search of a wind shield and in my opinion Europe and US are fast going to that craze point.
[1] - The perils of the fiscal cliff
[2] - Refer to United States debt-ceiling crisis

Friday, August 17, 2012

European Economic Crisis: France is the lion in the Grass


John Mauldin, a renowned financial expert, a multiple New York Times best-selling author, and a pioneering online commentator whose weekly e-newsletter  Thoughts From The Frontline reaches a million+ people, was in Singapore last month and he has given a speech  for OCBC Bank, called "The Lion in the Grass." In his article with the same name, The Lion in The Grass, he summarized this speech (follow the link and subscribe to his newsletter, he is one of the few unbiased economists in the world to get some good information).

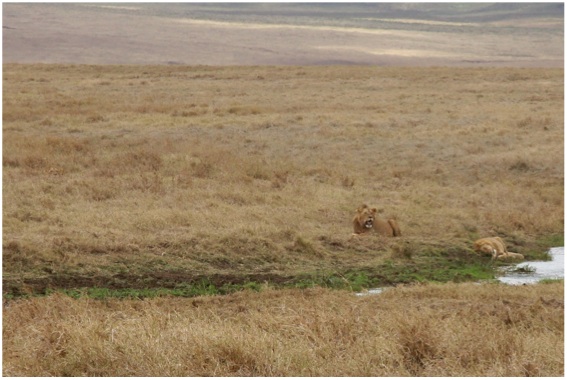
What John Mauldin says is that the lions we can see are not the real problems, we still have some chance to take action against them. The problem is the lion we do not see. The lion lying camouflaged in the grass and waiting for the time to attack and kill (see the photo below).

How many lions are there in this picture? 2? Look carefully and find the lion in the grass. There are 3 lions in this picture (look careful to the middle left).
- Source : The Lion in the Grass
We can now all see the lions, large and small, of Greece, Portugal, Ireland, Spain, Italy, and now Cypress and Malta. These are the visible lions of European debt crisis and attracts nearly all the focus. But Mauldin says that the real killer is the lion we cannot see, the lion lying in the grass. And that lion is France:

"Don't look now, but the lion that lies hidden in the grass is France. Yes, the France that is supposedly a big part of the solution to eurozone woes and Germany's stalwart partner in guaranteeing all that debt. AAA France. Rated that way by the same people who turned the nuclear waste of subprime CDO squareds, composed 100% of the worst sort of BBB junk, into gold.

...

It won't be this year or even in 2013 (I think), but within a few years we will be writing about France in the same way we are writing about Greece and Spain, et al., today. And French banks are massively larger than French GDP (some four times, or so I seem to recall). France cannot backstop its banks any more than Spain can.
"
Source : The Lion in the Grass

Tuesday, July 31, 2012

Pump, pump it up Ben, Pump it up a little more


"Get your boody on the floor tonight, make my day" - Pump up the Jam

Yesterday, Asian markets as well as Singapore stock market went up with the hope that money printers-in-chiefs Ben Bernanke and Mario Draghi will step up to save the day for the corrupted, non functioning, well debted but well connected part of the world economy again. Pavlov's alpha dogs, called investors in Bloomberg, and their equally stupid trading algorithms reacted cheerfully to the stimulus "hopes". It seems like Keynesian stupidity will rule the world for a long time.

Whenever I see these investors, dancing on the floor and drunk with the printed money out of thin air, I always remember the sexy hip hop artist Ya Kid K. and her famous techno song, Pump up the jam:

"Pump it up a little more (Ben)
Get the party going on the dance floor
See 'cos that's where the party's at
And you'll find out if you're too bad"

If you know economics only as much as Paul Krugman, which pretty much means you do not know economics at all, this stimulus party may look good to you. But the only thing it stimulates is the mal investment!

The main lesson for us all: Pumping up the jam may have an ugly end.

Think about it. For the man on the street, financial institutions and banks are parasites making money from money (sometimes from clients money, frequently from tax payers money). Yes, they have became parasites thanks to stimulus packages but being a parasite is not their purpose or function. In a free market economy free from moral hazards of a money printing central bank, their purpose is to channel savings to profitable investments. But they need a mechanism to differentiate profitable investments from the unprofitable ones. And interest rate is the mechanism used to separate a profitable investment from unprofitable investment projects. If you keep it artificially near zero levels, the mechanism will stop working and savings will be channeled to first profitable and unprofitable projects and then mostly to unprofitable ones! Enter the great malinvestment period of our last few decades. By keeping the interest rates around zero, maestro (!) Greenspan caused savings to be channeled to endless stream of property projects and fuelled the great financial crisis of 2008 in USA. And to save US, Bernanke is pumping money in the world economy and creating a great bubble in the world scale.

What is at stake is more than our finances: European and American central banks are basically destroying decades of accumulated wealth, mostly created by their fathers and grandfathers, by saving the day for institutions called too big to fail (which are actually too nonfunctional to not fail). And China, who never fails to imitate West and USA, is busy with destroying 3 decades of savings by pumping them into houses which will never be occupied, trains which will never be used and bridges which will never be crossed.

So, future does not look bright. But luckily, stock markets are holding well.

What pumps the stock markets up?


Asian stock markets cheerfully rallied yesterday with the hope that super money printers-in-chiefs Ben Bernanke and Mario Draghi will step in to save the day for the nonfunctioning, corrupted, well-debted but well-connected part of the economy with the expense of every functioning parts. Pavlov’s alpha dogs and their equally idiot algo-trading algorithms are cheering up whenever they see a stimulus package in the horizon. The cheer inflates every asset it can find on its way and then ends with a sure disappointment and expectations of more and more stimulus. It seems like all the world economy is taken hostage by hard core Keynesians (Keynesian economist is an economist who believes governments can create economic activity and save the humanity by "digging holes" and "filling those holes").  To just show how absurd, wrong and stupid the things are now just look at  Yanis Varoufakis’s article:
On 20th August, the Greek government will have to borrow 3.2 billion from one arm of the Eurozone (from the EFSF) in order to repay another (the ECB). Yet Greece is insolvent. The very idea of an insolvent entity borrowing more from a community, like the Eurozone, in order to repay that same community is obscene. All it does is to shift the burden from the Central Bank to the taxpayers of Germany, Holland, Austria and Finland. This is not an act of solidarity with Greece. It is an act of irresponsible kicking-the-can-up-a-steep-hill. The simple point I have been trying to drive home for a long while now is that the Eurozone must make a simple decision: Either to give Greece a proper chance of exiting its current death spiral. Or to dump Greece now, before the Greek state loses all its remaining assets and before it gets deeper into debt. And if our Eurozone partners are not prepared to make up their minds (caught up in their own short term concerns and shenanigans), then Athens must force their hand to decide within the next 23 days. How? By announcing that Greece will NOT be borrowing on 20th August monies it cannot repay under the present scheme of things.
Here is what we have written before:
If you know economics only as much as Paul Krugman, which pretty much means you do not know economics at all, stimulus news may look good to you. The only thing it will do is to stimulate mal investment to unproductive assets such as property and add up to huge public debt which is the number one reason of the lack of growth in the first place. The problem is that by keeping interest rates near zero levels. Central Banks are damaging the functioning of a financial system whose purpose is to channel savings to profitable investments. This is because interest rate is the mechanism used to separate a profitable investment from unprofitable investment projects. Here in Asia, where there is a huge lack of innovative investment projects, savings already tend to overflow to property. And with zero interest rates, they are flowing fast to properties. Although this means great gains for early private property buyers, for Asian economy, this amounts to a huge over investment to a relatively unproductive asset and is damaging for the economy.
Source : Singapore private property prices up again from Q2 2012
By creating money out of thin air and inflating the assets all we stand on, ECB and FED are making sure that we crash down from higher and higher altitudes and end up badly. This stupidity will end badly. I hope I am wrong.

Tuesday, August 9, 2011

What does zero interest until mid-2013 mean for Singapore?


Jim Rogers thinks that the man is an idiot. Rogers has a point, the man knows nothing other than printing money. If printing money could help "something" Zimbabwe would be the most prosperous nation on the planet now. But I think Bernanke is not an idiot he is just a man who assumes US public is idiot. He has to assume this because it is a prerequisite for his hard mission: saving his buddies on the Wall Street from even slightest pain even if this means damaging the productive parts of US and global economy. This makes him a very dangerous man rather than an idiot. He is really playing a dangerous game with other’s money:
“You know if you charge no interest, it’s pretty easy to make the interest payments...And then what would happen is the rates would eventually reset and the borrowers wouldn’t have the income to support the adjusted payments...A lot of the borrowers found themselves upside down and effectively in default.  
The same risk is true broadly for all sorts of borrowers public and private borrowers.  If we have zero rates in place for an extended period of time, borrowers become used to very small amounts of debt service that can cause them to become very over-extended and over-confident in how much debt they can handle.  If at a later time the interest rates end up resetting to a higher level, you can wind up with a real crisis.”
David Einhorn -  Federal Reserve Policies are Quite Dangerous
Since the men on the Wall Street grasp the free money and exports the inflation far away to Asia, he thinks he can provide free money until mid-2013. As expected, trading algorithms and investors cheered with FED’s commitment to provide free money at all cost. What does this mean for Singapore? Since Singapore is directly exposed to zero interest rate policy, this probably means more inflation, more dangerous asset bubbles and worse: more and more mis-allocation of Asian resources due to damaging high inflation - negative interest rate environment. FED is effectively pushing the global investors, especially the ones here in Asia to look for yield in risky assets. If they do not, they will lose cash to inflation so they will do. And this is not the best thing to do now, in an uncertain environment. And yes, property bubble may ride on to levels which dwarfs the pre-Asian Financial Crises numbers! 

Filling the economy with artificially free money and expecting people to make sound investments under these conditions is like filling yourself with bottles of alcohol and expecting to drive well back to home. In both case it is effectively a suicide:
“The housing bubble they inflated have blew up with all the carnage and all the bankruptcies. And now what is their solution: well just do the same thing we did before. Instead of having interest rates at 1 per cent, let's keep them at zero. And let's buy everything we can. Let's print money and buy mortgages, buy credit card debts, buy student loans. Let's buy bunds, let's drop money from helicopters to try to get to the same excessive risk taking and gambling on the Wall Street. Let's convince American's already loaded with huge debt to go and buy new stuff and go into deeper to debt. The banks do not want to lend money, let's make them lend more money. This is economic suicide."
Peter P. Schiff Euro Pacific Capital - Overdose: Next Financial Crisis

Monday, August 8, 2011

Overdose: The Next Financial Crisis


When will be the next financial crisis? In late 2011? 2012? 2013? Whenever it would be, it would be bigger than we had in 2008. The documentary named Overdose: The Next Financial Crisis, based on the book Financial Fiasco by Johan Norberg,  is "the story of the greatest financial crisis of our time;the one that is on its way." Although the corruption in financial world started in late  80s, this documentary chose to start narration from a later date, September 11 2001. In its nearly 46 minutes it shows how each bail out to rescue a part of economy caused another and larger bubble but still how the same failed solution is employed again:

"The solution is the problem, that is why we have a problem in the first place."
Vernon L. Smith - Chapman University

"The financial crisis (of 2008) started in a way that is very similar to today's situation. It started with an economic crisis in US (dot com bubble burst and 2001) and a government which responded decisively. After dot com bubble and 9/11, US government decided to save the economy by inflating a new bubble. Today the world is trying to get out of a financial crisis by inflating a new bubble. The difference is that this bubble is much bigger."

You can watch this documentary below. It is a must watch.


Here are some quotes from the documentary:

"Banks and speculators loved it (FED guarantee to clean up the mess). Now they could take greater risks then ever before. If they were successful they could keep the profits. And if they were unlucky, Greenspan will rescue them."

"We went on an unprecedented global spending bitch!Americans borrowed and spent trillions of dollars to buy staff. And that is why we are in so much problem now. That is because we were drunk and fed alcohol."
Peter P. Schiff Euro Pacific Capital

"Low interest rates caused the housing bubble. Cheap loans caused the people to buy more and bigger homes. House prices began to rise 10 percent a year. So many took out a second mortgage to fund consumption."

"Why do you need a decent income to buy a home if you can get rich by just living in it? The market even coined a term NINA loans. No Income, No Assets No Problem! You will get a loan anyway."

"Huge moral hazard created by the government in the mortgage market. When the government started to guarantee the mortgages, then the lenders stopped worrying about getting their money back, because the government said we guarantee it."
Peter P. Schiff Euro Pacific Capital

"They were great days. But it was all based on a market on steroids. Loans were cheap enough to keep driving housing prices up. But when interest rates returned to normal levels in 2006, the spell was broken."


"It is a pretty unlikely possibility, we have never had declining house prices in nationwide basis."
(Ben Bernanke answering a question back in 2005. The question is this: "Tell me what is the worst case scenario if in fact we see the prices come down across the country".Jim Rogers is right when he says this man has no idea about economics.)

"After they did the dot-com bubble and that burst, they re-inflated it with real estate bubble and when that burst, they have created the bubble of all bubbles. It is not only the United States now. This is a global bubble. They are all into it. It is called the bail-out bubble. Hey the economy is going down, recession is setting in, sales don't look good, exports soft, need more money. How about we call it stimulus package!"
Gerald Celente 
Trend Analyst Trends Research Institute

"The big guys on Wall Street. They cannot take their loses. They are cry baby capitalists. They preach capitalism to everybody but themselves."
 Gerald Celente 
Trend Analyst Trends Research Institute

"The housing bubble they inflated have blew up with all the carnage and all the bankruptcies. And now what is their solution: well just do the same thing we did before. Instead of having interest rates at 1 percent, let's keep them at zero. And let's buy everything we can. Let's print money and buy mortgages, buy credit card debts, buy student loans. Let's buy bunds, let's drop money from helicopters to try to get to the same excessive risk taking and gambling on the Wall Street. Let's convince American's already loaded with huge debt to go and buy new stuff and go into deeper to debt. The banks do not wanna lend money, let's make them lend more money. This is economic suicide."
Peter P. Schiff Euro Pacific Capital

"I was just very surprised that the people would accept the idea so readily (cash for clunker) not they have excepted the money, who wouldn't. That they have found this a viable solution. This does not give me a good impression of rationality of the voters and the tax payers."
Dr. Karen Horn
Head of Berlin Office IW Koln

"George W. Bush almost accumulated more debt then all US Presidents before him combined, from George Washington to Bill Clinton. And Obama is almost creating more debt than the all Presidents before him, including George W. Bush. 

Sunday, May 29, 2011

HDB resale flat prices are set to fall


What determines the price direction of an asset? In a relatively free market, supply and demand balance determines the price direction. You have more supply than demand then the prices tend to move down, you have more demand than the supply then the prices tend to move up. HDB resale flat prices moved up in the last decade because the demand exceeded the supply due to various reasons: economic growth, increase in PR approvals, reduced number of new HDB flats and low interest rates on mortgages between 2000 and 2010. Now some of these factors are changing direction:

More BTO units ahead. Since the introduction of BTO units in 2001, HDB decreased the output of flats to around 8,000 units per annum in the last decade from the average of 25,700 units per annum of 1990s. This was in response to the over-supply of HDB flats but resulted in a supply cut-back which did not match with the demand. In the recent years many  BTO projects got several times more demand than the supply. This made many couples looking for a home in resale market which also did not have enough flats due to lower number of new flats in the first half of the 2000s.

This was the hottest issue in GE 2011 and in response the government increased the release of new HDB flats to 22,000 for 2011. And the New Minister of National Development, Khaw Boon Wan, announced in new MND blog that he has ordered HDB to temporarily start building ahead of order since there is a backlog of demand. Increase in the number of new HDB flats will draw significant demand from the HDB resale market since many new weds would now have a chance to grap new flats with subsidized prices.

Just days into his new job as National Development Minister, Mr Khaw Boon Wan (picture) has instructed the Housing and Development Board (HDB) to build flats "ahead of demand" - a significant change in policy from the "Build To Order" (BTO) approach which has been in place for the past 10 years. 
Mr Khaw's announcement coincided with HDB's launch of six BTO projects - the largest number launched at once. In addition, he confirmed that the number of BTO units this year would be increased from 22,000 to 25,000 units, by bringing forward projects scheduled for early next year.
Source: HDB will build flats 'ahead of demand': Khaw
Income ceiling for new HDB flats. There are strong signals from the government that the first time HDB buyers income ceiling will be raised from 8,000 SGD per month to 10,000 SGD per month. Raising the ceiling will make many couples eligible to apply for BTO. Currently these couples do not have any other choice then to go to resale HDB or private property market. Once they have the option, demand for HDB resale flats will be reduced.


Interest rates. The last great money printing period of FED is about to end this June which was supposed to jump start the economy and reduce the unemployment. Well as expected, the only thing it could jump start was excessive speculation and since now US and Europe needs to cope with huge public debt and major Asian economies (especially China) are trying to reduce their trapped savings in US dollar, the interest rates will go up. Current interest rates are the main factor which makes severely unaffordable flats with prices 5 or 6 times the median income look "affordable".They were artificially kept low by Hedonist Western societies in the last decade to avoid the pain of their financial mistakes. This game will end soon and when it ends, the interest rates and monthly mortgage installments will go up which will reduce the demand for properties in all segments.


Number of PR approval per annum is decreasing and will not increase soon.  After steadily increasing from average of 35,000 approvals per year for 2001-2004 to its peak of 79,200 for 2008, it went down to 29,000 approvals for 2010. Many were expecting that decline in PR approvals would be a temporary trend until 2011 General Elections and after the elections trend would reverse. But during the election period, a significant number of Singaporeans made it clear that they are not happy with the current influx level of foreigners and it is very likely that the government will continue the downward trend in response to the sentiment on the ground.

Number of Singapore PRs approved per year (2001 - 2010)

Disclaimer
This blog article is to provide general information only and should not be treated as an invitation to buy or sell any property or as sales material.  Users of this report should consider this report as a one of the many factors in making their investment decision. Users should make reference to other sources of information and specific investment advice to obtain a more objective view of the property market. Asia Singapore shall not be responsible for losses suffered.

Monday, May 16, 2011

Fear the Boom and Bust - Hayek versus Keynes


Many of you probably know Keynes. He is the guy who teaches something like this: "If you wanna make glass-man wealthy you need to brake all glasses in the town." He thought spending creates wealth while in fact all the nations, companies and individuals in the history rose to glory on their or others savings. Who cares his ideas contradicts with the basics of economics like "finite resources", his ideas are politically convenient and very popular among western governments, technocrats and main stream managing the money. In the west it probably looks really cool to masses, "government spends money when people cannot".

There is another economic thought on the opposite site, Austrian School and Friedrich Hayek who teaches politically inconvenient hard realities of economics.

Econstories.tv created to excellent clips to explain the clashes of theories from these two opposite sites of economics. The tone of the clips do not try to hide on which side they are (these are pro Hayek clips).

"In Fear the Boom and Bust, John Maynard Keynes and F. A. Hayek, two of the great economists of the 20th century, come back to life to attend an economics conference on the economic crisis. Before the conference begins, and at the insistence of Lord Keynes, they go out for a night on the town and sing about why there's a "boom and bust" cycle in modern economies and good reason to fear it."


"According to the National Bureau of Economic Research, the Great Recession ended almost two years ago, in the summer of 2009. Yet we're all uneasy. Job growth has been disappointing. The recovery seems fragile. Where should we head from here? Is that question even meaningful? Can the government steer the economy or have past attempts helped create the mess we're still in?

In "Fight of the Century", Keynes and Hayek weigh in on these central questions. Do we need more government spending or less? What's the evidence that government spending promotes prosperity in troubled times? Can war or natural disasters paradoxically be good for an economy in a slump? Should more spending come from the top down or from the bottom up? What are the ultimate sources of prosperity?"


Sunday, December 19, 2010

Expat Living Singapore - The Expat Explorer Survey 2010


According to HSBC The Expat Explorer Survey 2010, Singapore is ranked 4th among 25 hot expat destinations in terms of key economic elements, income, disposable income and luxuries:

Singapore acts as an attractive location for high earners, which is unsurprising as it tops the economic league table on income score with nearly half (45%) of expats earning over $200,000 per annum compared to the worldwide average of just 21%. Expats based in Singapore benefit from lower tax than in their country of origin – only 8% believe they spend more on tax than they did at home. Of those surveyed, 61% also think that they have more disposable income than when living in their country of origin compared to an overall average of 42%.

However, with higher salaries and higher disposable incomes come higher costs; many think they spend considerably more than in their country of origin on accommodation (72% in Singapore vs. 46% overall) and food and drink (60% vs. 47%).

Expats in Singapore also believe they are already seeing signs of an improved economy, with over half (51%) agreeing that the economic situation in Singapore has improved since last year (compared to 22% overall). They are also much less worried about having to monitor spending (8% in Singapore compared to an overall average of 23%) or reduced career opportunities (15% vs. 20%).

[Expat Exlorer Survey 2010, Page 22]
Taxes in Singapore are very attractive. Actually, one of the main reasons behind Singapore's huge percentage of expats with higher disposable incomes is Singapore's tax system. Singapore imposes one of the least rates of personal and corporate income tax, enabling its residents to retain a higher portion of their income. Singapore's personal income tax rate starts at 0% and is capped at 20% (above S$320,000). The corporate income tax rate is approximately 8.5% for profits up to S$300,000 and a flat 17% above S$300,000. The Expat Explorer survey cites that 61% of the 109 expats surveyed in Singapore think that they have more disposable income than they would had they been living in their country of origin[1]. Last year I have paid around 6 percent of my gross income with a salary just below 100K (yes I do not belong to the >200K expats group yet). Around 20% of the same income would go as tax in my country of origin. Also I pay 7% VAT in Singapore which is 18% for most of the goods in my original country.

I agree with the cost of accomodation, it is very expensive and eats up a considerable amount of your income. But for me, the food and drink are cheaper in Singapore. I do not drink alcohol a lot (which is very expensive in Singapore due to taxes) and I eat in cofee shops and food courts a lot where you can find good and cheap food.

Singapore is also getting costlier. According to Expat-Essentials Singapore is costlier for expatries now. ECA International found that Singapore is the eighth-most expensive city in Asia for expats. Singapore was placed No. 9 last year. Globally, Singapore is the 42nd-most pricey a huge jump from from 79th last year. In Asia, Singapore is behind the likes of Japan, Hong Kong, Beijing, Shanghai and Seoul. And things will get costlier according to ECA. Inflation and a strong currency will continue to drive expats’ costs in Singapore ever higher next year.


According to the survey the wealth gap between East and Europe is widenning. This survey shows that the wealth is moving to the East. The Middle East, Singapore and Russia dominate the top quartile of the Wealth Hotspot leader board, while expats in mainland Europe and South Africa are accumulating the least amount of financial wealth:

Expats in Russia remain the wealthiest in the world, with 36% of expats in Russia earning over $250,000. This number has actually increased over the past year – 30% of expats based in the country earned over $250,000 in 2009. Both Singapore (32%) and Bermuda (27%) also have a much higher proportion of expats with an annual income of over $250,000, significantly higher than the overall average of 13%.

Mainland Europe, however, dominates the bottom five positions on the Wealth Hotspot league table. Almost two-thirds (62%) of expats living in Spain earn below $60,000, as do almost half of the expats living in France (47%), the Netherlands (47%) and Germany (45%). This is much higher than the global average of approximately one quarter (26%) of expats earning below this figure across the world. In fact, the only other country to join mainland Europe in the bottom quartile was South Africa, where around one-third (36%) of expats earn less than $60,000.
[Expat Exlorer Survey 2010, Page 5]